Full-Doc Jumbo
- Who it's for
- W-2 earners, professionals and owners with strong tax returns buying above the conforming loan limit.
- How you qualify
- Tax returns, W-2s and pay stubs, with reserves sized to the loan amount.
Business owners, investors and high-net-worth families finance on bank statements, assets, rental income or full documentation. Your file gets structured by someone who reads a P&L the way you do.
Borrowers, agents and CPAs on what it's like to close with Funded by Vic.
Most declines in this price range are documentation problems, not credit problems. The tax return says one thing and the bank account says another. The fix is choosing the right way to show income before anyone pulls credit.
Write-offs shrink taxable income, and that's the number a conventional underwriter uses. Bank statement and P&L programs qualify you on what the business actually deposits.
Qualify on the property's rent, not your personal income. Close in an LLC, scale past the conventional property count, and pull equity for the next deal.
Retired, between ventures, or living off a portfolio. Liquid assets can stand in for income, and full-doc jumbo stays on the table when W-2 income is strong.
You'll know which program fits and roughly what you qualify for before you send a single document.
Fifteen minutes on how you earn, what you hold and what you're buying. No credit pull.
A one-page memo with the recommended program, estimated qualifying income and the exact documents needed. Typically within one business day.
Your file goes to the wholesale lenders whose guidelines fit it best, then gets managed through closing with your agent and CPA in the loop.
Self-employed buyer with a thin tax return. Client who just sold a company. Investor with eight properties and a DTI problem. Send the scenario and you'll get back a written structure your client can act on.
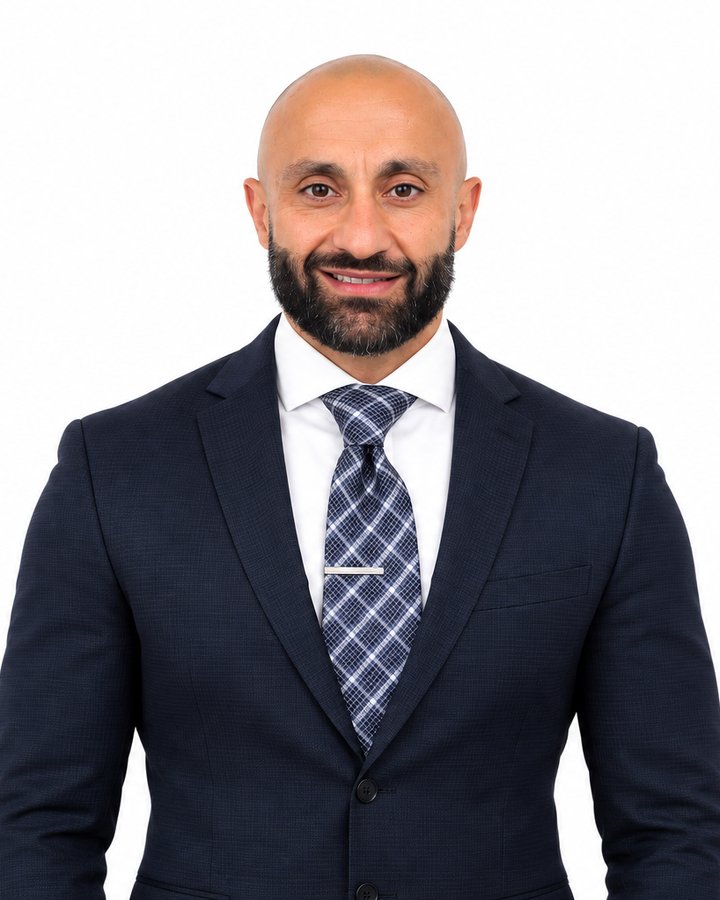
Before mortgages, Vic sold hospitality investment real estate at Marcus & Millichap and ran Sync Brokerage as Managing Partner. That background is why files get read the way an owner reads them: cash flow, assets and the deal behind the deal.
Today he originates jumbo and non-QM loans at Loan Titan for self-employed and high-net-worth borrowers across Los Angeles, and documents the build on his YouTube series, The Road to $75M.
Weekly video, conversations with LA's top agents, and a biweekly brief on what's moving in local lending.
A weekly documentary on building a $75M mortgage practice in Los Angeles.
LA's luxury agents on listings, buyers and what gets big deals to close.
Biweekly. Partner interviews and a lender's read on the LA market.
The right program depends on how you earn and what you hold. Every program is shopped across wholesale lenders, so the structure fits your file instead of one bank's box.
Not every file is complicated. Conventional, VA, equity and construction loans run through the same desk, with the same speed.
Conforming and high-balance loans for primary homes, second homes and investment property.
For eligible veterans and service members, including loan amounts above the conforming limit.
Pull equity without touching the first mortgage you already have.
A lump sum against your home's equity, repaid on a fixed schedule.
A revolving line against your equity. Draw what you need, when you need it.
Ground-up builds and major renovations, from land to certificate of occupancy.
Fast, asset-based short-term financing for deals that can't wait on a bank or don't fit any box.
Program details vary by lender and change often. All loans are subject to credit approval, underwriting guidelines and property eligibility. This page is not a commitment to lend.
A weekly documentary on building a $75M mortgage practice in Los Angeles. Mindset, the daily frequency, deals in motion and the people who make them happen.
Conversations with the agents who move Los Angeles' most expensive homes. Listings, buyers, negotiations and what actually gets a big deal to close, from the lender's side of the table.
Each episode spends forty minutes on one market story: a hard listing, a shifting neighborhood, a buyer who changed everything. You bring the deals, I bring the financing angle.
Agent partner interviews and a lender's read on the Los Angeles market. Two minutes, every other week.
A few lines is enough. You'll hear back with the program that fits and what to gather next.
Your scenario is on Vic's desk. Expect a call or email within one business day. Need it faster? Call or text 310-499-8918.
Here's your scenario. Send it by email or copy it into a text to 310-499-8918.